The Bill With No Postcode: Selling Fast When a Chancel Check Raises Its Hand
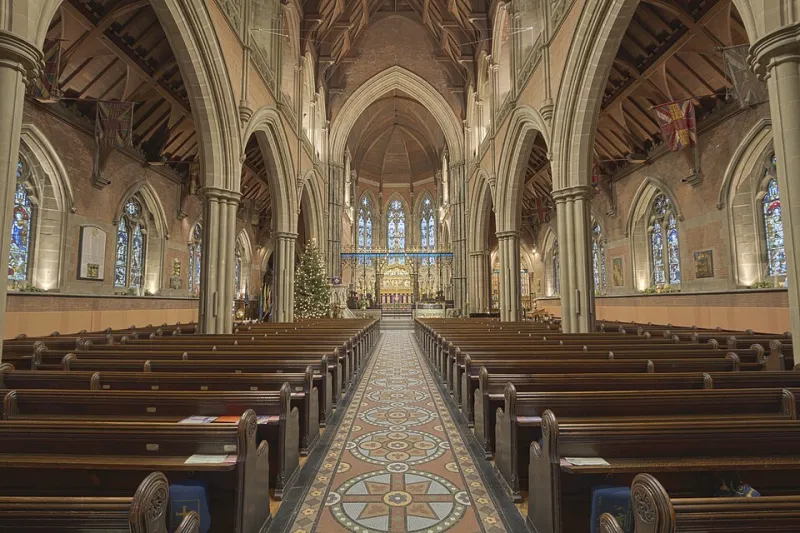
Photo: Mdbeckwith, CC BY-SA 3.0, via Wikimedia Commons
Most property searches are boring in the best possible way. Drainage, radon, a bit of noise from the A-road — you read them, you nod, you move on. Then the chancel repair search lands and everyone goes quiet. It mentions a parish, a possible liability, maybe a registered notice. Your buyer’s solicitor wants answers. Your lender wants comfort. And you’re looking at a completion date that suddenly feels less like a plan and more like a hope.
What chancel repair liability actually is
Chancel repair liability is an old obligation attached to some properties in England and Wales. In simple terms, it can require owners of former rectorial land to contribute towards repairs of the chancel — the east end of a Church of England parish church. It is not a service charge, not a council tax add-on and not a modern estate fee. It is a historic liability that can, in theory, be shared among affected properties and can be uncapped. That last word is why lenders sit up.
It is also rare. Plenty of searches come back with no issue at all. Some come back with a parish that has historical links but no registered liability. Others show a registered liability or a notice that needs proper legal reading. Those are very different outcomes, and the difference matters enormously when you’re trying to sell quickly.
Why it spooks a fast sale
A mortgage lender wants a clean, predictable title. Chancel repair liability introduces a question mark: could the church authorities ask this owner for money, and how much? Some lenders are relaxed if an indemnity policy is in place. Some want a retention. Some want the buyer to take it on the chin with a price adjustment. A few simply don’t like it. When you’re selling to a buyer with a mortgage, that caution can add days or weeks — exactly what you don’t need when you’ve already got a moving date.
The buyer, meanwhile, is hearing the words ‘ancient liability’ and imagining a bill with no ceiling. Most people don’t know what a chancel is, let alone whether they should care. Your job is to replace that fog with facts.
The 2026 version of the paperwork
The law changed back in 2013. Since then, a chancel repair liability generally needs to be registered at Land Registry to bind a buyer who purchases for value. If it wasn’t registered, a later buyer may not be bound by it. That sounds like a clean escape, but don’t treat it as one without your solicitor’s view. Searches can still flag a parish connection, lenders can still ask questions, and a cautious buyer can still walk away if nobody explains the position properly.
So the first step is not panic. It’s a proper read of the search result, the title register and any notice. Ask your solicitor to tell you, in plain English, whether this is:
- a registered liability that affects the property;
- a parish risk with no registered liability; or
- something that needs a further search or legal opinion.
That answer decides everything else.
Three levers that keep a buyer engaged
1. Get the indemnity quote early
Chancel repair indemnity insurance is often the cheapest way to take the sting out of a search result. Policies vary, and they don’t erase the liability — they cover the cost of dealing with a claim or legal challenge, subject to the policy terms. For a fast sale, the trick is to have a quote ready before the buyer’s solicitor asks. It shows you’re not hiding anything and gives the lender a document to consider. Ask your solicitor to arrange it, and check whether your buyer’s lender accepts that particular policy.
2. Treat a price adjustment as a line item
If the liability is registered or the risk is real, a modest reduction can be cheaper than losing three weeks to a nervous lender. Don’t frame it as a disaster. Frame it as a known cost that’s now been priced. A buyer who feels informed is far more likely to proceed than one who feels ambushed. If the numbers are uncertain, ask your solicitor whether a retention or an undertaking could bridge the gap.
3. Keep the cash route in your back pocket
A cash buyer can be the calmer route when a lender starts dragging its feet. That’s not because cash buyers ignore legal risk — a sensible one will still take advice and may price the liability in. It’s because there’s no mortgage condition to satisfy. The deal can move on a clear legal position, an indemnity policy or an agreed adjustment. If your timeline is tight, it’s worth getting a cash offer alongside the mortgage sale so you have a fallback that doesn’t depend on a lender’s mood.
What a sensible week looks like
Week one: get the search, the title and your solicitor’s plain-English note. Week two: get an indemnity quote, disclose it to the buyer and agree how to handle it — policy, price or both. Week three: if the lender is still circling, decide whether to hold, adjust or switch to a cash buyer. The worst move is to let silence fill the gap. A buyer who hears nothing imagines the worst.
The bottom line
Chancel repair liability is niche, old-fashioned and occasionally annoying. It is not a reason to write off a sale. Get the facts, get the policy quote, and put a number on the risk. If the mortgage route stalls, a cash buyer can keep the clock moving — as long as you vet them properly and disclose everything. At QuickSell Houses, the rule is simple: a fast sale isn’t about hiding problems. It’s about solving them before they become someone else’s excuse to delay.