What the Council Never Saw: Selling Quickly When the Extension Paperwork Isn't There
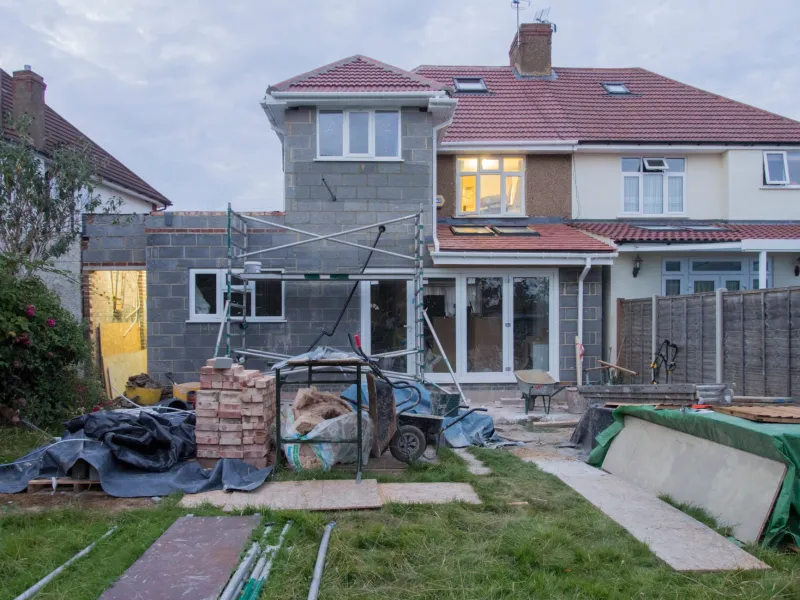
You know the room is sound. You've had eleven Christmases in it, the radiator works, the roof hasn't leaked once. What you don't have is a completion certificate saying so. Somewhere between the builder packing up his van and the final invoice being paid, the building control inspection slipped, and now you're selling and the paperwork isn't there.
That's a common position, and it's rarely the disaster sellers fear. But it does need handling deliberately, because missing sign-off touches three separate people in the chain — the buyer, their lender and their solicitor — and each one reacts differently.
Start by working out what's actually missing
"No paperwork" gets used as shorthand for several different problems, and they don't carry the same weight.
Planning permission is about whether you were allowed to build it. Plenty of extensions never needed it — permitted development covers a lot of single-storey rear work — but the tricky ones are the projects that crept over the limits, or where a neighbour's objection triggered an enforcement notice.
Building regulations are about whether it was built properly: foundations, insulation, structural openings, fire safety, drainage. This is the one that shows up as a missing completion certificate, and it's the one lenders care about most, because it goes to the safety and value of the habitable space.
Some sellers have one and not the other. Some have neither. Dig out whatever you've got — planning decision notices, architect's drawings, structural calculations, photos of the build at each stage, the builder's details — before you speak to anyone. A file with something in it reads very differently to a shrug.
If the work is old enough to be beyond any enforcement window and you simply want certainty, a lawful development certificate confirms the planning side. It won't fix building regs, though. Nothing does except regularisation.
How buyers react in 2026
The first thing that happens is the local authority search. It flags whether a completion certificate was issued for work at the property, and it lands on the buyer's solicitor's desk early. There's no hiding it, and trying to is a bad idea — a buyer who finds out late starts wondering what else wasn't mentioned.
Most buyers take it in their stride if the extension looks and feels right. A garden room that's clearly a garden room, well built, no damp, no cracks — people shrug. A two-storey side extension with a big structural opening into the main house draws sharper questions, and rightly so.
What buyers really want is a story that makes sense. Who built it, when, what inspections did happen, and whether anyone has ever queried it. If you can answer those, the conversation moves on quickly.
The lender question
This is where timelines bend. A mortgage valuation isn't a full survey, but a valuer who spots an extension with no sign-off may note it, exclude it from the valuation, or flag it for the lender's attention. Some lenders will proceed regardless. Others want a certificate, an indemnity policy, or a structural engineer's report before they'll release funds.
If the unapproved space is doing real work in the valuation — a loft bedroom, a kitchen extension — expect the lender to look harder. If it's incidental, like a small conservatory or a shed conversion, it usually washes through.
The practical upshot for a fast sale: ask your agent early whether your likely buyer pool is cash or mortgaged. It changes the whole plan.
Indemnity insurance: cheap, quick, and often misunderstood
An indemnity policy is the shortcut most conveyancers reach for. For a modest one-off premium — often a few hundred pounds — it covers the buyer against enforcement action by the local authority over unauthorised work.
Two limits matter enormously. First, it protects against enforcement, not against shoddy building. If the extension is genuinely defective, the policy is irrelevant. Second, most insurers won't touch a property where the council has already been approached about the work, or where an enforcement notice exists. Once you've made an enquiry, the indemnity route usually closes.
So the order of operations is important. Speak to your solicitor about indemnity before you ring the council asking friendly questions. That one phone call can be the difference between a £200 policy and a regularisation application.
Regularisation: slower, sturdier, sometimes the only way
Regularisation is the formal route: you apply to the local authority for a certificate on work already done. A building control surveyor inspects, may ask for sections of the build to be opened up, and either certifies it or lists what needs putting right.
It's not quick. Think weeks rather than days, and opening up work costs money. On a loft conversion with a dodgy stair headroom or missing fire doors, the bill can climb into four figures before you've sold anything.
But it gives you something an indemnity policy never can: a clean, sellable property with no asterisk. If your buyer is mortgaged and nervous, or the work is significant, that certainty is often worth more than the time it costs — and it usually pays back in the price.
Then there's the price
Where the paperwork is missing and the seller won't fix it, buyers price in risk. Not always dramatically — a small discount for the hassle — but it's real, and it gives you leverage to negotiate in the other direction if you do have a certificate.
Be honest in the listing. "Extension completed, completion certificate available" is a strong line. "Extension with no building regs sign-off, priced accordingly" is a weaker one but far better than letting it surface at search stage, three weeks in, when your buyer's solicitor asks the question and your buyer's confidence drops through the floor.
The quick-sale route
Cash buyers are, bluntly, more comfortable with this scenario than mortgage lenders. They're not answering to an underwriter. They price the risk in, complete on what's there.
If speed is the priority and regularisation would push you past a deadline, a cash sale is a legitimate answer — just go in with your eyes open about the discount, and be ready with the file you've assembled. Serious cash buyers will ask the same questions a surveyor would.
A realistic timeline
Rough shape, if you act today: a week to gather documents and get advice on indemnity versus regularisation. If indemnity works, exchange in the normal flow, four to eight weeks for a mortgaged buyer. If regularisation is needed, add two to three months onto the front, and consider marketing while the application runs so you're not starting from cold when the certificate lands.
Missing sign-off isn't a wall. It's a bend in the road, and the earlier you see it coming, the gentler the turn.